
Sprott Radio Podcast
Fixing the Nuclear Duration Mismatch
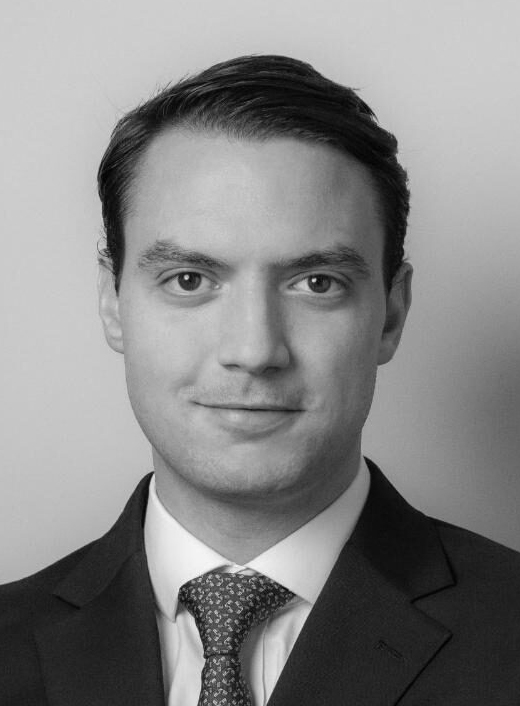
Nuclear power is having a moment, yet installed capacity globally has barely moved. In this episode of Sprott Radio, Ed Coyne is joined by Ben Finegold, director at Ocean Wall Ltd., to unpack what Ben calls the "duration mismatch": public-market investors think in quarters and years, while nuclear reactors and uranium mines take a decade or more to build. Ben explains why that gap matters for investors, how it can be bridged, and where he sees opportunity across the nuclear value chain.
Podcast Transcript
Ed Coyne: Hello, and welcome to Sprott Radio. I'm your host, Ed Coyne, Senior Managing Partner at Sprott. Today, I'm pleased to welcome a new guest to our show, Ben Finegold, director at Ocean Wall Ltd. Ben, thank you for joining me today on Sprott Radio.
Ben Finegold: Great to be here, Ed. Thanks for having me on.
Ed Coyne: Of course. Ben, as a new guest on our show, I always like to get a sense of who you are, what brought you to the world of nuclear, and learn a little bit about Ocean Wall. What's your day-to-day there? What are you guys working on?
Ben Finegold: Absolutely. Ben Finegold, director at Ocean Wall. We're a merchant bank based in London, with offices in Dallas as well. The merchant part of that means we build our own internal convictions around certain themes and invest in those ideas ourselves. We try to identify the most interesting ways to express themes we are convinced of, and there is definitely no theme we are more convinced of than nuclear power and nuclear fuel.
We were established in 2019. My role has been principally on the nuclear side of things, looking at research and establishing that conviction, but also trying to originate some interesting ideas and get the world as bought into the nuclear thesis as we are.
Ed Coyne: Did you start embracing nuclear as an investment thesis in 2019 with Ocean Wall, or was that something you brought to the table?
Ben Finegold: Great question. I worked for an investment club whose members were ultra-high-net-worth individuals, and my job was to identify interesting ideas in public markets for them to consider for their portfolios. It was 2020 when Nick Lawson, the founder of Ocean Wall, presented the uranium thesis to the investment club I was working with, and my boss told me, "Go and find some interesting ways to play uranium."
That sent me down a six-year rabbit hole. Nick and I got chatting about things, and I just said, "This is what I want to do." I had a passion for markets, and the energy transition and the nuclear thesis just made a lot of sense to me. In 2021, I moved to Ocean Wall. We were a team of four at the time, and we had just started writing about the uranium thesis through a nuclear lens.
Ed Coyne: That brings up a good point because in the last half a decade or so, we've seen uranium go from roughly $30 a pound to more than $90 a pound. Some would say, "Gee, that's a huge run-up in a relatively short period of time, albeit very volatile." If there's a listener on the call today that says, "Hey, did I miss this?" What would you say to somebody then? Over the last five years, we've seen a lot of activity, news flow and price appreciation. Where do you think we actually are? Is this the beginning? Are we in the middle? Where are we in that cycle, in your view?
Ben Finegold: I think what's been amazing is we've seen a destocking event over the last six years, and I think that's primarily been what's driven pricing up. What I would say to anyone looking at the uranium thesis today is that installed nuclear capacity is basically unchanged globally. If we separate the two and look at what's going to drive uranium prices higher, it's new reactors coming online and reaching criticality. When we look at new reactors coming online and reaching criticality, there's been virtually no growth in installed capacity over this period.
Even during this period, we've seen prices rise from $20 a pound to $100 a pound. This is in the wake of the fact that we haven't had this major build-out. What's going to drive this next leg is actually us fulfilling our nuclear ambition, moving the industry from good rhetoric, good headlines, and good policy to actually getting electrons to the grid.
Ed Coyne: I guess the first thing is we had a bunch of reactors that were set to be shut down, and then that changed. We hear all these things about more than 25 new reactors coming online in China. We had the first new reactor in Georgia in over 20 years come online. You're hearing other things about what Amazon's doing in Indiana, with potentially new build-outs. All these things are starting to happen. From the work you're doing, when do you see that start hitting the market and new reactors on the grid where they're actually plugging them in? Where are we in that cycle then? When do you see that start to happen?
Ben Finegold: We've seen a lot of the low-hanging fruit be picked, and by the low-hanging fruit, I'm talking about extensions, restarts, vis-à-vis building a new large-scale gigawatt project. These have much shorter time periods and lower capital investment. We've seen that with Microsoft's agreement related to Three Mile Island, and we're now starting to see it with uprates, which are much lower-hanging fruit. The promise of uprates is very simple. You don't have to build out new capacity. It's just making what already exists more efficient, and there are some interesting examples of that.
To your point about China, it is really walking the walk to an extent, and it's not alone. India, Canada, Korea, Japan, and Russia, via their build-own-operate model, are the main contributors to what we see as the nuclear growth trajectory over the next decade or even two. I think the market has become completely obsessed with just the U.S. story because, obviously, that's a lot of what drives sentiment in public markets, but there's going to be a single-digit growth rate across nuclear, irrespective of whether the U.S. brings online its 10-pack of Westinghouse reactors. This is just additive, and we'll also talk about the role AI plays in this sector.
To your point, Ed, the turning point is when the low-hanging fruit has been picked, and I think that we're largely there and uprates will continue, but ultimately, it's going to be when industry is forced to decarbonize, where it's no longer just nice to have, where hyperscalers are putting nice MOUs together with the advanced nuclear industry. That's not what gets projects done. What gets projects done is proper capital commitments under binding contracts, and we talk about moving from rhetoric to actual delivery.
Ed Coyne: You mentioned something about "decarbonization," and we were talking about this before we started the call. That term hasn't really been spoken out loud for the last 24 months. Then we've got AI, data, hyperscalers and all that coming online. Are those two at odds with each other, or are they working in conjunction? You mentioned AI and data a moment ago. Is that going to drive it? Is decarbonization going to drive it? What do you think is going to be the primary driver of this narrative?
Ben Finegold: I think such is the attention span of the modern world that it was not too long ago that this term of decarbonization was on everyone's lips; investors, industry, everyone in the world. Then this new term came around called AI, and it was just forgotten about. It was power at all costs, regardless of how it was delivered or how clean it was.
Two or three years ago, if you were a hyperscaler with a 2030 net-zero ambition, your AI ambition and your carbon or climate ambitions were just on a collision course. There was internal debate about how we would mediate between the two. Then at some point, it just became irrelevant. It was, "We do not care what type of power it is," and that's why we've seen gas and coal really be the poster child for powering the modern wave of data centers.
Those two things were on a collision course. I think the market is now waking up to recent events. Will the Democrats in the U.S. slow down the growth rate around AI? Will they force cleaner sources of energy to come into the fray for hyperscalers and reset to the mentality that the world had only a few years ago, which was, "Yes, we want to see AI succeed. We understand that much of the domestic GDP in the U.S. and other Western economies will be attributed to AI. That's amazing, but can it necessarily be to the detriment of our decarbonization ambition?"
I think we overcorrected in the other direction, and we'll start to revert toward the mean. That is not to say that data centers currently using gas or coal will have to be shut down. I don't believe that. I believe that nuclear has been a nice option for hyperscalers to date, not necessarily a mandate, whether internal or at the government level, for these corporates and industries to decarbonize.
Ed Coyne: A lot of these tech companies, such as Amazon and Microsoft, are all becoming involved in this in a more direct way. It seems they understand they're probably not just running into an energy problem; they're facing a PR problem. When you think about who's getting the electricity, is it just going to go to the highest bidder, and is this going to squeeze out the consumer in something as simple as heating and cooling their home? In your work, what is starting to come out of that? Are people talking about that, or is that just a back-channel narrative?
Ben Finegold: The most high-profile case of this was Talen Energy and Amazon, which was essentially that ratepayers are ultimately going to feel the burden of what was essentially ratepayer-funded nuclear now being transferred to use cases. What we have seen is that every hyperscaler, whether it's Microsoft, Amazon, Oracle, or Meta, has made some commitment to nuclear power, and that's no accident. It is recognition that their data centers require five-nines reliability, and the only clean source of power that gets them anywhere near that is nuclear and, to an extent, geothermal, but in terms of established power today, it is nuclear.
To highlight the Talen-Amazon deal with Susquehanna in Pennsylvania: AWS bought Talen's data center campus, which sits next to Susquehanna, with about 2.5 gigawatts of capacity, for $650 million. The plan was to do behind-the-meter supply that would ramp up to nearly a gigawatt, but the Federal Energy Regulatory Commission (FERC) rejected the expanded interconnection agreement for co-location. This was the first major regulatory test that hyperscalers faced when taking power directly from a nuclear power plant. Then the promise became SMRs, and let's go behind the meter, and let's go off-grid.
Look at the way TerraPower has evolved: from "We're going to be a behind-the-meter supply industry" to having 5.5 hours of storage, which is much better used by plugging into the grid. I do think there's going to be a behind-the-meter use case, but equally, the preference, particularly at the government level, is always to plug into the grid and ensure that the consumer is not the one paying for AI. The promise of AI should be, and we've seen this with AI dividends, where data centers generating meaningful wealth within local areas are distributed among the community. That can be this utopia within AI, and it shouldn't come at the expense of the consumer.
Ed Coyne: That's interesting because I have not read much about that. If you're new to this space as an investor, what is the number one misunderstood concept behind what's happening in nuclear today? Is it the reactors? Is it the suppliers? Is it the refiners? Is it the enrichers? What should people understand if they're going to walk away from this in five minutes and say, "Hey, maybe I should be thinking about this." What would you tell somebody who's misunderstood, and what should they be thinking about?
Ben Finegold: If we think about the nuclear build-out, separate from uranium, we talk about a duration mismatch. For us, the duration mismatch is evident in the number of nuclear companies that, in a previous life, would never have been public companies, rushing to market because U.S. equity markets are handing out $1 billion in free cash at incredibly lofty valuations. The attention span of public market investors, whether hedge funds, retail investors, specialist funds, or institutions, very rarely matches the time it takes to build nuclear power.
I think it's the same for uranium: How long does it take to build a uranium mine? Is the patient capital there that really understands what they own, that understands that mining is hard and that things go wrong, that understands that there are regulatory hurdles that need to be overcome, like Amazon and Talen, when you want to bring online new capacity? To any investor coming into this space, just really understanding what it is that they're buying.
When we started looking into nuclear, the term that was always used was "it moves at a glacial speed." I think that the world, particularly in the Western world, has made great strides in expediting permitting and licensing across mining and power, but ultimately, these are very large infrastructure projects, and they do take time.
The number one thing I have learned over the last couple of years, in particular, is that the natural pools of capital you would go to for a gas project or for established energy projects don't really exist, at least not to the same degree, in nuclear power. That is because, aside from names like Brookfield, large infrastructure funds do not have 50 projects to look at over the last 10 years and say, "This was the project that went wrong. This is why it went wrong. This is why it went right. I understand the cost of capital. I understand how to price this risk."
When you're looking at a $10, $20 or $30 billion project, you have to understand the risks associated with it. We don't necessarily have the scar tissue that other large energy projects do. I say that because the opportunity is to sit with the world's largest sovereign wealth funds and institutional investors, and some of these investors don't have a nuclear investment framework.
We're going to launch a conference in the spring, the Ocean Wall Nuclear Investment Summit, dedicated to one question: if you are an investor looking at this space, what are your options? Project-level equity, project-level debt, listed equities across the fuel cycle, the supply chain, waste or decommissioning? There is this entire array for investors coming into the space now, beyond just uranium, but actually the entire nuclear value chain, and we do see value across that entire universe.
Ed Coyne: We talked about this again before the call today: the ecosystem of conferences in this space has really taken off in the last five years. One of my colleagues, John Ciampaglia, and I have talked in the past about how much that has evolved. In your experience, go back five years and talk about what a uranium or nuclear conference looked like, versus what it looked like coming out of the conference season just now. How different is that in the last five years? Who's attending that? What kind of investors are attending that?
Ben Finegold: I'll take you back to the World Nuclear Symposium in London in 2021, which I think was my first time attending. It was a room of, let's say, 150 of us. I would say 95% were industry participants. I had an interesting chat with Grant Isaac at Cameco when he was in London. He spoke about how Cameco used to come to WNA, and their entire day was filled with industry meetings. They were meeting with fuel buyers and their colleagues across the build-out supply chain, and it's now almost like an investor conference.
Fast-forward to today, it's 900 people this year. You've got hyperscalers, the oil and gas industry and a huge investment community. By the way, that's just the 900 who buy tickets for the conference. I would say 80% of my meetings are with people who haven't bought a conference ticket but are in town because they know everyone else is. There are probably thousands of investors in London that week who are there solely for nuclear power.
I say this because in 2021, I built a basket that looked at the entire collective market cap of the uranium industry, and it was $12 billion. That is uninvestable for large institutions, apart from Cameco at the time, then SPUT, and, over time, NexGen. I say that because today, that same basket is $150 billion.
Ed Coyne: Wow.
Ben Finegold: In that five-year period, we have seen a tenfold increase in the investable universe just in uranium. Cameco was a $40-odd billion market-cap company on its own through this year. I say that because these conferences have changed: the sector has become investable for public market investors, thanks to greater choice, greater liquidity, and, ultimately, greater interest in the sector.
Ed Coyne: It's interesting when you compare it to other industries like tech. Yes, it's had this tenfold expansion, but it is still tiny. From an investor's point of view, that's a great example: yes, we've had some exciting news, moves, and profits, but it still feels like we're in the very early days. The market is just waking up to this; capital is just starting to show up and companies are going public. All these things are just starting to happen. It's an established industry, but it also feels like a new frontier. Do you agree with that? Just talking to you, it feels like we're on the precipice of a new frontier evolving here in this space.
Ben Finegold: I think it would lack credibility to say that we're right at the beginning, because we're not. The industry has made meaningful progress over the last five years to de-risk its nuclear ambition. However, I go back to what I said at the beginning: how much has installed nuclear capacity actually changed over this five-year period? The answer is very little, and if you remove China from the equation, zero, or maybe even negative growth.
If you were to look at this from a global, ex-China perspective, you could thank Germany for part of it. I say that because it's on the nuclear build-out side, but if we focus just on uranium, we're still in the early innings of a new contracting cycle. We haven't hit this replacement rate level, whatever it is: 185-190 million pounds of primary demand. It's November 10. We are at 83 million pounds of reported total contracting in the term market this year, well under 50% of the replacement rate. Yet this year, we have only seen uranium term prices rise.
The most interesting conversation, and in answer to your question, Ed, about how those conferences have changed, is that the one thing that hasn't changed is my conversations with utilities. In 2021, I said to them, "Are you worried about the future supply of nuclear fuel?" They said, "No, we're well covered. Absolutely fine." You have the same conversation with them in 2026, and they say the same thing, but they're paying a 400% premium for the same fuel.
Ed Coyne: Still not worried. It's a relatively small cost relative to the profitability of a reactor, correct? It's under 10% of the feedstock itself.
Ben Finegold: Yes, it's obviously increased with prices. We've seen a four- to sixfold increase across the fuel cycle, including U3O8, conversion and enrichment. A lot of the downstream has been a function of Russia's invasion of Ukraine. I know we'll talk about market bifurcation, but what is going to drive that next leg higher is actually, in our view, the cost curve, because a lot of these producers are just being forced higher and higher up the cost curve as a result.
Maybe prices have doubled or tripled, but if you look at Kazatomprom, for example, the world's largest producer, in its IPO prospectus or in its reported cash cost for 2018, the all-in sustaining cost has gone from $15 per pound in 2018 to $40 in 2026. Yes, uranium prices have moved, but so have costs.
Ed Coyne: The margins haven't really expanded as much as one would think, given the price escalation of the actual U3O8 itself?
Ben Finegold: Correct. Which means there's more money in the system, which means the sector grows. Another thing we talk about is: imagine a cargo ship traveling from St. Petersburg to the East Coast of the U.S. Think pre-Russia's invasion of Ukraine: how much of that cargo was oil and ancillary commodities like lumber and timber, versus uranium?
Uranium is a tiny part of these ships. Transport has become a major concern for many of these nuclear fuel producers because why insure the most dangerous item on the ship when it accounts for only 2% or 1% of the total cargo? We used to see four cargo ships running that route from St. Pete's to the East Coast. There's now one. A lot of that has been a function of Kazakhstan, in particular, having to transport much greater volumes of its Western exports via the Trans-Caspian Route, which is another conversation altogether.
Ed Coyne: Let's stick with the theme of the East versus the West, because I think this is true in a lot of metals. When you talk about precious metals, particularly gold, there's a bifurcation between the way the West thinks about it and the East. It seems like it's a little closer with uranium, but are you seeing two separate developments, two separate markets, two separate ecosystems start to build out when you talk about Western consumption and production versus Eastern?
Ben Finegold: Absolutely. We spend a lot of time covering Kazakhstan. For any listener who wants our report on Kazakhstan, it's completely free, and we're very happy to send it. We have actually visited Kazakhstan, which I think very few Western bankers can say they have. What we've learned is that about 80% of Kazakhstan's total uranium exports are locked up under offtake agreements with India, China and Russia.
You couple that with the fact that, in the last couple of weeks, the government has set out an ambition to build a 100-year stockpile of uranium for its own domestic nuclear ambitions, in which it's looking to build up to four nuclear reactors. You then realize that 40% of the global uranium supply, in OPEC+ terms, is locked up in the East alone. Then you look at a country like Uzbekistan, which has made meaningful progress in ramping up production to about 7,500 tons and aims to double it.
Now let's look at the nuances of that region. It’s very acid-intensive, as is well documented. Uzbekistan's well fields require twice as much acid as Kazakhstan's, so its domestic shortage of sulfuric acid becomes a major problem for ramping up production, or, at the very least, it pushes production higher up the cost curve. Then, in Kazakhstan as well, you have a mineral extraction tax that essentially incentivizes higher prices and disincentivizes higher production. You start to see that this is what contributed to the more than twofold increase in all-in sustaining costs.
You then look at the Western world and see a U.S. industry that has made progress in ramp-up but is still producing 2 million to 2.5 million pounds a year, compared with 50 million pounds of domestic consumption. You go to your northern neighbor in Canada, and you say, "We're running a 90% deficit as a U.S. nuclear fleet for U3O8. Have you got any pounds for sale?" You go to Cameco, and Cameco says, "We're pretty much sold out through the next four years, through 2030." Therefore, you really are reliant, much more so than anywhere in the world as a Western utility, on greenfield production.
For any listener on this podcast who understands mining, you know that mining very rarely comes in on time or on budget. We are relying on companies such as NexGen, Denison, IsoEnergy, Paladin and PLS, the old Fission asset, for the stars to align and for everything to go well, and maybe the deficit will shrink.
As we think about the supply-demand setup, it is not equal in the East as it is in the West. We have yet to see that reflected in pricing, so we are not seeing a premium for U.S.-provenance pounds yet. If you look at the NNSA, it's the U.S. agency that procures nuclear fuel for the defense industry; it's just issued an RFI for 4 million pounds of U.S.-only production. That's twice the current annual U.S. production, nothing to do with power.
Ed Coyne: You mentioned the greenfield versus brownfield. Greenfield effectively is a brand new discovery or a brand new mine versus Cameco or Kazatomprom saying, "Hey, we've got a mine. Let's expand upon it and see where else we can find stuff." Am I right to believe that it takes a decade or more? Let's say you can make a discovery today; you're talking 10 years minimum before you're pulling anything out of the ground? What does that actually look like?
Ben Finegold: I like using this example, not just because it illustrates the point, but because it's real and it's in action today. Fission Uranium Corp discovered PLS, a 90-odd-million-pound high-grade deposit very near NexGen's Arrow. They discovered that back in 2012. It won't produce until 2032 at best. It's a 20-year lead time. These projects take a very long time to reach production, and that is in the best uranium market in the last five years. It's not because they're struggling to attract financing, because there are investors queued up around the block to fund these projects. It's about the technical know-how.
Particularly in the Western world, we were self-sufficient in nuclear fuel. Take the U.S., for example. They produced 40 million pounds of uranium a year. That has shrunk by 90% because this goes back to the Megatons to Megawatts program, which involved the downblending of Russian weapons-grade uranium.
Most people don't know that this program, Megatons to Megawatts, downblended 20,000 nuclear warheads after the collapse of the Soviet Union, and it fed the entire U.S. nuclear fleet for over two decades. They didn't need mining, conversion or enrichment. It was just going to live on cheap Russian nuclear fuel forever. I want to mention one thing I forgot. Namibia, as a top-five global producer, is pretty much exclusively locked into Chinese offtake as well.
Ed Coyne: It looks like we've got a long way to go. Yes, it's at the beginning of the cycle, but between discoveries and between East and West, and this is all before new demand even comes online. We're talking about existing demand. I know a lot of people talk about what people are used to seeing, the large reactors, the AP1000s, that kind of thing. Can you talk a little bit about technology?
People who are paying attention talk about modular reactors, small modular reactors and microreactors. We've been talking about this for a couple of years now, but how real is it to come online, go into production, take supply out of the market, and compete with the large traditional reactors? Give us a timeframe on that. How real is that?
Ben Finegold: I would say 2026; if you had to define this year, it's going to be the year when SMRs take over the large build. I say that because I really think the SMR industry is walking the walk more than large gigawatt-scale projects have been, particularly in the West. We saw more than four of these SMR projects reach criticality in the U.S.
We've seen these projects attract billions in private capital from industry, its customers, and capital markets to fund these first-of-a-kind projects. Names like X-energy and Oklo in public markets and even private names like Kairos and TerraPower have just made meaningful progress. TerraPower is starting construction of its first project in Wyoming. Very simply put, the promise of SMRs is to apply production-line economics to nuclear power: Henry Ford, the Model T, modularization, and prefabrication.
For the investment community in particular, infrastructure investors, whoever it is, it's just less scary than going up against a $20 billion nuclear build, and there are very different models. Take the Oklo approach: they want to be the developer. They're going to go on risk as the developer for the first-of-a-kind project, whereas X-energy is leaning more toward a licensing model, trying to reduce balance sheet risk slightly and share risk with their customers. Whatever the approach, the industry has made meaningful progress across the SMR space.
Ultimately, we now need to see that we're talking about a duration mismatch. In our opinion, the way to resolve the duration mismatch is for customers to pay for these projects, since there is no mismatch in duration. It is customers saying they want power within this timeframe. They go to the nuclear power SMR company, whatever it is, and they say, "Delivery in 2035. Can you get it done?" They go on that journey together.
That is not to say that nothing's happening in the gigawatt-scale industry. EDF, the bastion of European nuclear power, is now sending its engineers to China on secondment to learn how China is building these reactors in less than five years. It can be done, but it's got to be a fleet approach. Intuitively, if you want to build 10 reactors in the U.S., the first one is going to be the most expensive, and the 10th is going to be the cheapest.
Why not have a cost share across all 10? I'm not telling the U.S. government something they don't already know, but it does require utilities to collaborate; it requires engineering and procurement firms to work hand in hand. I don't want to be this echo chamber that we hear at conferences: "Let's collaborate. We need more collaboration."
The one thing I can't reconcile is that hyperscalers are paying two to three times the wholesale electricity price for clean baseload power. You can screw these projects up as much as you want. The margin that you're going to make as the IPP is going to be good enough regardless, because you've got Google, Meta and Microsoft all queuing up, paying huge premiums for the power that you can produce.
Ed Coyne: I hate to keep going back to the well on the AI data, but effectively that's what you're starting to see happen. Microsoft, Amazon, Meta, they're all stepping up and financing these projects in ways you wouldn't have thought would happen before. You would have thought utilities were going to provide the power; Amazon's going to be the consumer. They seem to be partnering now.
To me, what you just described is what we've already been seeing over the last six months to a year. I suspect that more of those types of deals will be announced over the years. People are excited about Westinghouse. Are they going to go public? What does that look like? It's fascinating that this is now becoming a melting pot of private industry, public companies, and utility companies working together. Do you think that's going to continue, or are these just one-off, knee-jerk reactions?
Ben Finegold: What will affect the most change is nuclear not just being a nice-to-have, but nuclear being a must-have. Meta or Amazon is writing a $50 billion check to these businesses; these guys need billions of dollars to get to work. Just as you see hyperscalers delivering billion-dollar upfront prepays for gas-powered shells, they'll have to do the same for nuclear.
Ed Coyne: We talked a lot about the positive side of what can go right. I feel like I'd be dishonest if I didn't say what could go wrong. Let's say we're in this trade; the capital's flowing. What would be a bear case scenario where we could all get surprised and say, "Gee, it's not just volatility. This is going to draw down for a prolonged period of time." Are there some scenarios where you could see that happening as well?
Ben Finegold: Yes. I think if we focus on the uranium side, Kazakhstan ramped up production from zero pounds in the early 2000s to become the world's largest producer within a decade. Does another Kazakhstan out there exist that is running a major exploration program to try to do the same? Our view from our work is no, but if you take what the Uzbeks are saying as gospel, they could contribute an extra 10-15 million pounds of supply to the market by 2030. I think it's just about constantly keeping an eye on it, as we do with any tail risk in the uranium supply sector.
The other thing that will impact that is the demand side and whether there is a slowdown in demand, because in the Western world, we really haven't built it for the last two decades. As a risk, does this take longer than expected? Do we have an established supply chain? Do we have a labor force capable of actually building this next generation of nuclear power plants?
The way that we think about solving that is, first of all, the globalization of the workforce. There's a lot of discussion about Korea coming to the U.S. to help build AP1000s or APR1400s. Ultimately, one of the great success projects of the last decade was in Abu Dhabi, where the Koreans did exactly that. A slowdown in the growth trajectory, meaning uranium supply catches up with demand. Again, we think it's unlikely, but it's possible.
Then another thing we get asked about regularly is breakthroughs in areas like fusion. Ultimately, I don't want to be dismissive enough to say it's always 10 years away. We've spent time at Culham Campus at the UK Atomic Energy Agency here in the UK, which is our champion of the fusion industry, and there are very realistic, super smart scientists and engineers who are realistic about fusion's ability to deliver gigawatt-scale power in the near term. I don't see it as a tail risk to the sector today. A breakthrough in fusion could potentially change that.
Then maybe the only remaining risk is nuclear meltdowns, and I don't see the reactors themselves failing to be safe. In a world that is now riled up by geopolitical tension, whether it's Russia sending rockets into Zaporizhzhia to the Ukrainian nuclear power stations, or whether it's Iran and Israel, or whether it's the U.S. and Iran, there is a global conflict where potentially nuclear power could be used as a weapon, but we keep our fingers crossed that that doesn't become a reality. We have learned that these power plants can, to date, withstand the brutalities of war.
Ed Coyne: That poses a problem not just for this industry. Those kinds of bear-case scenarios pose a problem for industries worldwide. I guess that's one thing that's worth considering. Were there any other topics that you think our listeners would benefit from that you were hoping to talk about today that I didn't address?
Ben Finegold: Keeping a forensic eye on the cost curve is really important. I would echo what our great friend at Sachem Cove, Mike Alkin, said during his speech at NEI, which is that globally, producers are being pushed higher up the cost curve, whether that's Kazatomprom or the rest of the industry; companies like Boss, I think, have gone from the mid-$20s a pound to over $50 a pound. The NexGen OpEx figures have gone from, I think, about $8 CAD to close to $15 CAD. Paladin as well, from mid-$20s to over $60 in their latest accounts.
While you might not see huge moves in uranium prices on a daily basis, we are seeing meaningful moves up on the cost curve. On the uranium side, that's the thing that I would note most. In the physical build-out, there are brilliant businesses that will contribute to the nuclear build-out. If we are to realize our nuclear ambition, a $5 trillion CapEx cycle will create a $10 trillion market. Who are the companies that stand to benefit as a result of that build-out? We think about it as betting on the race, not the horse. There's no better way to bet on this race, in our view, than physical uranium.
If you look at the build-out, which companies will supply the reactor pressure vessels and the heavy forgings for this physical build-out? There is a large investment universe. We track about 150 listed companies in the nuclear industry that are investable for public-market investors. There is a world, I would say, just beyond looking at whether it's just uranium or just looking at miners, that there is an investable universe out there where we see great value.
Ed Coyne: Ben, thank you. This has been really great, and it's amazing. I've probably done nearly 20 podcasts specifically about uranium and nuclear issues, and I continue to learn more with each one, which is great. Hopefully, our listeners walk away from that as well. Good luck with the conference. I guess that's happening in the spring, if I heard that correctly?
Ben Finegold: Exactly. It will probably be mid-April. We'll post about it on our LinkedIn for anyone who wants to take a look.
Ed Coyne: You also mentioned a couple of reports that you guys have. How would they find you, learn about the work you are doing, and learn more about Ocean Wall?
Ben Finegold: If you are a retail investor, we have a Substack with a weekly note dedicated to the nuclear industry. It's called The Hoot. It will be on our Twitter, I assume. Then, if you are an institutional investor or a family office, please feel free to email me at ben@oceanwall.com. We have a weekly research product we can share with accredited investors, called Ocean Wall's ion-U. That's a weekly newsletter we've been writing since 2021. We also have various thematic reports on Kazakhstan, transport, and acid, and we're happy to share them if possible.
Ed Coyne: That's really great. Ben, I appreciate you carving out the hour for us. Again, I really enjoyed talking with you, and I hope we get to meet in person someday. Again, thanks for taking the time today.
Ben Finegold: Thanks, Ed. Anytime.
Ed Coyne: Thank you all once again. My name's Ed Coyne, and you're listening to Sprott Radio.


Important Disclosures
This podcast is provided for information purposes only from sources believed to be reliable. However, Sprott does not warrant its completeness or accuracy. Any opinions and estimates constitute our judgment as of the date of this material and are subject to change without notice. Past performance is not indicative of future results. This communication is not intended as an offer or solicitation for the purchase or sale of any financial instrument.
Relative to other sectors, precious metals and natural resources investments have higher headline risk and are more sensitive to changes in economic data, political or regulatory events, and underlying commodity price fluctuations. Risks related to extraction, storage and liquidity should also be considered.
Gold and precious metals are referred to with terms of art like store of value, safe haven and safe asset. These terms should not be construed to guarantee any form of investment safety. While “safe” assets like gold, Treasuries, money market funds and cash generally do not carry a high risk of loss relative to other asset classes, any asset may lose value, which may involve the complete loss of invested principal. Furthermore, no asset class provides investment and/or wealth “protection”.
Any opinions and recommendations herein do not take into account individual client circumstances, objectives, or needs and are not intended as recommendations of particular securities, financial instruments, or strategies. You must make your own independent decisions regarding any securities, financial instruments or strategies mentioned or related to the information herein.
While Sprott believes the use of any forward-looking language (e.g., expect, anticipate, continue, estimate, may, will, project, should, believe, plans, intends, and similar expressions) to be reasonable in the context above, the language should not be construed to guarantee future results, performance, or investment outcomes.
This communication may not be redistributed or retransmitted, in whole or in part, or in any form or manner, without the express written consent of Sprott. Any unauthorized use or disclosure is prohibited. Receipt and review of this information constitute your agreement not to redistribute or retransmit the contents and information contained in this communication without first obtaining express permission from an authorized officer of Sprott.
©Copyright 2026 Sprott All rights reserved